Dubai Tax: Understanding the Changing Business Landscape
Understanding dubai tax requirements has become an important consideration for businesses operating in the emirate. Dubai is known for its dynamic economy, international business environment, and growing number of local and global companies. As the UAE continues to develop its taxation framework, businesses need to understand applicable requirements and incorporate tax compliance into their regular financial management practices.
Understanding the Tax Environment in Dubai
Dubai’s business environment includes companies from numerous industries, including construction, retail, technology, logistics, hospitality, finance, healthcare, and professional services. Each business may have different financial circumstances and regulatory responsibilities.
Tax requirements can depend on factors such as the nature of business activities, legal structure, income, transactions, and applicable regulations. Businesses should therefore assess their individual position instead of assuming that the same rules apply to every company.
Why Businesses Should Pay Attention to Tax Compliance
Tax compliance is an essential part of responsible business management. Companies that maintain proper records and understand their obligations can manage their financial responsibilities more efficiently.
Good tax management can help businesses:
- Maintain organized financial records
- Prepare required documentation
- Monitor important deadlines
- Improve financial planning
- Reduce administrative errors
- Understand their potential tax obligations
- Make better-informed business decisions
Taking a proactive approach is generally more effective than dealing with tax matters at the last minute.
The Importance of Proper Bookkeeping
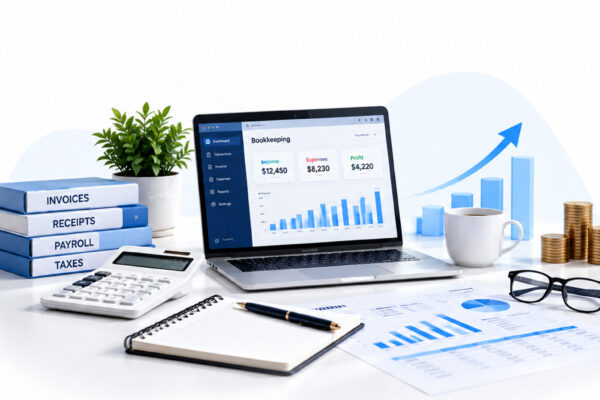
Accurate bookkeeping is one of the foundations of effective tax management. Businesses should record income and expenses systematically and keep appropriate supporting documents.
Invoices, receipts, bank statements, contracts, payroll records, and accounting reports may all form part of a company’s financial documentation.
Regular bookkeeping also gives business owners a clearer understanding of revenue, expenses, profitability, and cash flow.
When financial information is properly maintained throughout the year, preparing tax-related information becomes considerably easier.
Corporate Tax Considerations
Businesses operating in Dubai should understand whether their activities and income fall within the applicable UAE corporate tax framework.
The tax treatment of a company can depend on several factors, including its structure and activities. Companies should review their circumstances carefully and seek professional advice where the rules are complex.
Corporate tax should also be considered when businesses prepare budgets, forecasts, and long-term expansion plans.
VAT and Business Transactions
Businesses may also need to consider VAT obligations depending on their activities and circumstances. VAT can affect pricing, invoicing, accounting procedures, and financial reporting.
Companies should maintain proper VAT records and ensure that transactions are accounted for appropriately.
Businesses involved in frequent purchases, sales, imports, exports, or other commercial transactions should pay particular attention to maintaining accurate documentation.
Role of Professional Tax Advisors
Tax regulations can be technical, particularly for companies with complex financial structures or international transactions. Professional advisors can help businesses understand relevant requirements and establish suitable compliance procedures.
Tax professionals may assist with registration, tax return preparation, financial reviews, documentation, tax planning, and general advisory services.
For small businesses without dedicated finance departments, professional support can be especially helpful.
Tax Planning for Growing Businesses
Tax considerations should form part of a company’s growth strategy. Businesses planning to expand their operations, open new branches, establish additional entities, or enter new markets should evaluate potential tax implications in advance.
Early planning can help management understand expected financial commitments and prepare appropriate cash-flow strategies.
It can also help businesses avoid making structural decisions without considering their potential tax consequences.
Common Tax Management Challenges
Businesses can encounter several challenges when managing tax obligations. One common problem is incomplete financial documentation.
Other challenges may include incorrect accounting classifications, missed deadlines, poor recordkeeping, or misunderstanding applicable requirements.
These issues can often be reduced through regular financial reviews and professional guidance.
Businesses should also ensure that their accounting systems are suitable for the size and complexity of their operations.
Staying Prepared for Regulatory Changes
The regulatory environment can develop over time. Businesses should therefore monitor relevant updates and review their internal processes when necessary.
Companies that regularly review their tax and accounting procedures are better positioned to adapt when requirements change.
Professional advisors can also help businesses understand how new developments may affect their operations.
Building a Strong Financial System
A good financial system should provide accurate information throughout the year. Businesses can establish procedures for recording transactions, reviewing accounts, organizing documents, and monitoring compliance requirements.
Larger organizations may have dedicated finance and tax teams, while smaller businesses may rely on external accounting and advisory professionals.
Regardless of the company size, consistency is important.
Conclusion
Understanding tax responsibilities is an important part of operating a successful business in Dubai. Companies can benefit from maintaining accurate financial records, reviewing their obligations regularly, preparing ahead of deadlines, and obtaining professional guidance when necessary.
A proactive approach to taxation can support better financial management and reduce unnecessary compliance risks. With proper planning and organized accounting practices, businesses can focus on their long-term objectives while managing their regulatory responsibilities effectively.