Light and Ultralight Aircraft: Expanding Recreational Aviation and Flight Innovation
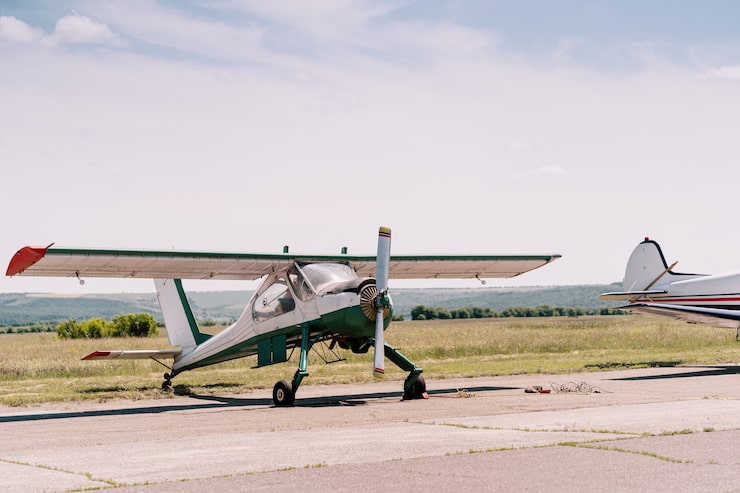
Light and ultralight aircraft are gaining attention across recreational aviation, pilot training, private travel, aerial observation, and specialized flying activities. Their comparatively compact designs and operational flexibility make them suitable for applications that do not require larger commercial aircraft. As interest in sport aviation grows and manufacturers explore advanced materials and alternative propulsion technologies, this segment is evolving to serve a wider range of aviation needs.
According to the Global Light and Ultralight Aircraft Market report by MarkNtel Advisor, the global industry was valued at USD 10.75 billion in 2025 and is projected to reach USD 21.89 billion by 2032, registering a CAGR of 10.69% during 2026–2032. Light aircraft accounted for 65% of the market in 2025, while conventional take-off and landing (CTOL) aircraft held a 74% share. North America led regional demand with approximately 37%, supported by its established general aviation ecosystem and recreational flying infrastructure.
Recreational Aviation and Pilot Training Support Demand
Recreational flying remains an important driver of demand for light and ultralight aircraft. These aircraft appeal to aviation enthusiasts, private owners, flying clubs, and training organizations because they can support leisure flying and flight instruction without requiring the scale of larger aircraft. Their use also extends to sightseeing, local aerial observation, and other specialized activities.
Pilot training contributes to demand by creating a need for aircraft that can be used regularly for basic flight instruction and skill development. Flying schools and clubs depend on reliable aircraft availability, manageable operating expenses, and access to maintenance services. Growth in aviation participation can therefore support demand for new aircraft as well as replacement models and aftermarket services.
The Federal Aviation Administration’s guidance on light-sport aircraft outlines certification and consensus-standard information relevant to this category in the United States. Regulatory requirements influence aircraft design, pilot privileges, maintenance procedures, and the types of operations that can be conducted. These factors are important considerations for both manufacturers and prospective owners.
Light Aircraft Maintain a Leading Position
Light aircraft represent the largest type segment in the MarkNtel Advisor report. Their versatility makes them suitable for recreational flying, pilot training, aerial surveying, and selected civil, commercial, and government activities. Compared with ultralight models, certain light aircraft configurations can offer greater payload capacity, range, and passenger accommodation, depending on the aircraft design and certification category.
Ultralight aircraft serve a different set of requirements, often emphasizing simpler construction, recreational use, and accessible flying experiences. Their specifications and operating limitations vary by jurisdiction, meaning manufacturers must consider local definitions and certification rules when developing products for international customers.
The distinction between the two categories is commercially significant. Aircraft capabilities, acquisition costs, maintenance requirements, and permitted uses can influence customer selection. Manufacturers that align their designs with clearly defined user needs and applicable aviation standards can address distinct segments of the general aviation sector.
CTOL Aircraft Dominate Flight Operations
Conventional take-off and landing aircraft accounted for approximately 74% of the global industry in 2025. Their established operating model allows them to use existing runways, small airstrips, and regional airport infrastructure. This reduces dependence on specialized facilities and supports their use in recreational flying, training, and cross-country travel.
Vertical take-off and landing (VTOL) technology represents another area of aviation development. However, VTOL aircraft can involve different engineering, operating, infrastructure, and certification requirements. Their future role will depend on technological progress, intended applications, operating economics, and the regulatory pathways available in individual countries.
Electric and Hybrid Propulsion Create New Opportunities
Electrification is an emerging trend in light aircraft development. Electric and hybrid propulsion systems are being explored for their potential to reduce direct operating emissions and noise in suitable applications. Progress in electric motors, energy storage, power electronics, and lightweight materials could influence future aircraft designs.
However, adoption depends on practical considerations, including battery performance, flight range, payload, charging infrastructure, system reliability, and certification. Conventional propulsion remains important, particularly where operating range and established support networks are priorities. Manufacturers must evaluate these trade-offs against the requirements of intended users rather than treating alternative propulsion as a universal replacement.
Regulatory Requirements and Competitive Landscape
Aviation regulation remains a significant consideration for this industry. Certification standards, pilot licensing, maintenance obligations, and operating permissions differ across jurisdictions. The European Union Aviation Safety Agency’s light-sport aircraft guidance illustrates how aircraft specifications and approval pathways shape the requirements applicable to this category in Europe. Differences between national frameworks can increase compliance complexity for manufacturers seeking to sell internationally.
The competitive landscape includes Astronics Corporation, Cirrus Aircraft, Costruzioni Aeronautiche TECNAM S.p.A., Textron Inc., Pilatus Aircraft Ltd., Aeropro Ltd., American Legend Aircraft Company, Autogyro GmbH, Evektor-Aerotechnik a.s., Flight Design General Aviation GmbH, Jabiru Aircraft Pty Ltd., CubCrafters, Inc., Pipistrel d.o.o., Quicksilver Aircraft, and Air Création.
Overall, the outlook for light and ultralight aircraft will depend on recreational aviation participation, training demand, regulatory developments, and improvements in aircraft technology. Manufacturers that combine suitable aircraft performance with reliable maintenance support and compliance across target markets will be better positioned to respond to evolving general aviation requirements.